How to Turn Accounting into a Tool for Addressing Environmental Challenges
What is accounting? It is, above all, an information system designed to aid decision-making and ensure accountability. It is therefore not just about seeing, but about seeing in order to act in an era increasingly referred to as the Anthropocene. This term refers to the period in history beginning when human actions began to have as great an impact on ecosystems as natural forces.
Christelle Chaplais, Clermont Auvergne University (UCA); Bastien David, University of Montpellier; Eugénie Faure, Audencia and Nicolas Antheaume, University of Nantes
The term implies concerns about the long-term sustainability of human societies. Our work explores three dimensions through which accounting can capture the impact of human activities on the environment and provide a basis for action.
The donut as a benchmark
The hypothesis of an unprecedented climate—or even geological—upheaval, which scientists refer to as the Anthropocene, should prompt everyone, individually and collectively, to rethink the way they act, consume, and travel. The scientific assessment seems radical and highlights just how much human activities impact the environment.
It must be acknowledged, however, that it is extremely difficult today to determine to what extent each action and each behavior contributes to slowing down or accelerating the consequences of the Anthropocene. Without a common frame of reference, how can we enable everyone to set goals for themselves and understand where they stand?
There are many frameworks designed for businesses. They are primarily used by large corporations that are required to disclose non-financial information in their reporting documents.
Some private international bodies are generally in favor of covering only companies’ ESG impacts (environmental, social, and governance impacts), using a simple materiality approach: in other words, their sole objective is to inform investors about the risks associated with these companies, as measured by ESG criteria.
On the other hand, the European Union is seeking to establish a framework for non-financial reporting that takes into account “double materiality”—that is, an analysis that incorporates both the impact of a company’s ESG risks and the company’s impact on society. However, the link between financial and non-financial reporting remains tenuous.
Oxfam France
At a minimum, the information provided makes it possible to determine a company’s carbon footprint or its contribution to the UN’s Sustainable Development Goals. However, very few reporting frameworks allow us to understand how a company stacks up against the targets set by scientists—targets that, quite simply, determine the future of life on Earth!
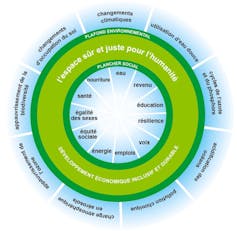
Many people today are calling on organizations to change course and adopt a common framework —for example, by considering the “doughnut theory ” when preparing their financial statements.
This approach, developed by British economist Kate Raworth, frames corporate activity between a social and societal floor—which acknowledges that we cannot sacrifice everything in the name of the environment—and a ceiling corresponding to the planetary boundaries popularized by Swedish researcher Johann Rockström and his co-authors.
To provide a common methodology
This common methodology can only be effective if it is supported and promoted by an organization that serves asa legitimate authority. An example of such an organization is the French Accounting Standards Authority (ANC).
To be legitimate, an authority on Anthropocene accounting should involve both the producers and users of accounting information, drawing on recognized scientific knowledge.
No authority based on this model exists today. In reality, there are a multitude of normative proposals, most of which are non-binding. A legitimate authority could be responsible for:
- develop standards for the disclosure of environmental information;
- provide a methodology, an accounting system, and the units of measurement (physical, monetary, or other) needed to collect, calculate, or estimate the information. This could be an opportunity to propose units that are not monetary but are consistent across all impacts. One could consider, for example, measuring the number of years a company has left before its impacts prevent it from continuing to operate normally, once it has already consumed its share of viable economic space;
- provide a framework for presenting this information and give users access to the assumptions and calculation methods;
- ensure the traceability of the information produced and its verifiability in the context of an audit;
- define the possible penalties for failure to comply with these obligations.
Bill Baue, an American expert on reporting issues, is even calling for the creation of an authority that would go a step further and be tasked with allocating planetary threshold quotas to individual entities. He proposes calling it the GTAC, which stands for “Global Thresholds for Allocation Council.”
It affects us all
By providing accountability and supporting decision-making, accounting makes the responsibilities of the various stakeholders transparent. Organizations and consumers alike must therefore be able to understand the limitations imposed on them.
For the Anthropocene to be apparent to a decision-maker within an organization, that decision-maker must have access to information that concretely helps them understand the consequences of their decisions on the state of natural environments and society.
A decision-maker must therefore have the tools to simulate the consequences of their choices: What will be the impact of a particular type of packaging (cardboard, glass, etc., whether reusable or not), a product formulation (liquid or solid), or a supplier (location, country of origin, supplier’s wage policy)?
Alexas_fotos/Pixabay, CC BY-SA
The same applies to consumers. Accounting will make the Anthropocene visible if it can translate the act of purchasing into a contribution to an environmental burden or to the achievement of a social goal. In this regard, there is still significant work to be done on the measures to be implemented to support this effort, particularly through product labeling.
The ultimate measure of success will be when our behavior has internalized the Anthropocene to such an extent that it becomes both present and invisible.
This article was written by a group of researchers as part of a collaborative “speed blogging” event held on the sidelines of the CSEAR France/EMAN Europe 2021 online academic conference. The speed blogging exercise involved collaboratively writing an article within a limited time frame on the conference theme, “Sustainable Development Accounting in the Anthropocene.” At the end of the event, three articles were co-authored by established researchers, junior researchers, and doctoral students..
Christelle Chaplais, Professor in audit and accounting ethics, Clermont Auvergne University (UCA); Bastien David, Ph.D. candidate and Associate Professor of Economics and Management, University of Montpellier; Eugénie Faure, Ph.D. candidate in multi-capital accounting for SMEs, Audencia and Nicolas Antheaume, Professor of Accounting for Sustainable Development, University of Nantes
This article is republished from The Conversation under a Creative Commons license. Readthe original article.